Can you keep the hail check and not fix the car?
Sometimes, and the answer comes from your policy and, if the car is financed or leased, from your lender, not from a repair shop. In Kansas the check for a repairable car is issued in your name, and the dents you were paid for stay on the car for the next claim and the next sale.
Who is the hail insurance check made out to?
For a car that will be repaired, the Kansas Insurance Department's Auto Insurance Shopper's Guide says the claim settlement check is issued in your name. A repair shop's name goes on it only if you authorize that.
A lender is a different matter. Kansas law lets you name the lienholder listed on your title when you apply for comprehensive or collision coverage (K.S.A. 40-955(g)(1)). Whether that lender's name then appears on a hail check is decided by your policy and your loan or lease contract. Look for the lender on your policy paperwork before the check arrives, so you know whose signature it needs.
Can my lender make me fix the car?
That answer lives in your loan or lease contract, not in insurance law, and we are not going to guess at it. A lender listed on your title has an interest in the car. Read what your contract says about insurance money and repairs, and if it is silent, ask the lender in writing before you deposit anything.
If the car is leased, the leasing company is part of this too. Kansas even requires a lessee to tell the lessor within 30 days if the car is found to be a salvage vehicle (K.S.A. 8-198(d)(4)). Read the lease before you decide anything about the repair.
Do I get the same amount if I don't repair the car?
Kansas regulation answers part of this. Under K.A.R. 40-1-34, an insurer shall not settle on a cash basis for less than it would pay if repairs were made, other than in a total loss, unless you agree to the lower amount. The department's guide adds that the offer needs to cover the actual repair costs to restore the car to its pre-loss condition, and that the company does not have to settle on the highest estimate.
The weak point is the estimate itself. Hail is routinely under-counted on a first look, and on a repair the missed dents are documented and sent in as a supplement. Before you take cash on a first estimate, ask for a copy of it, which the same regulation says the insurer gives you when it prepares one, and ask your carrier whether a supplement is still possible later.
What happens if hail hits the same car again?
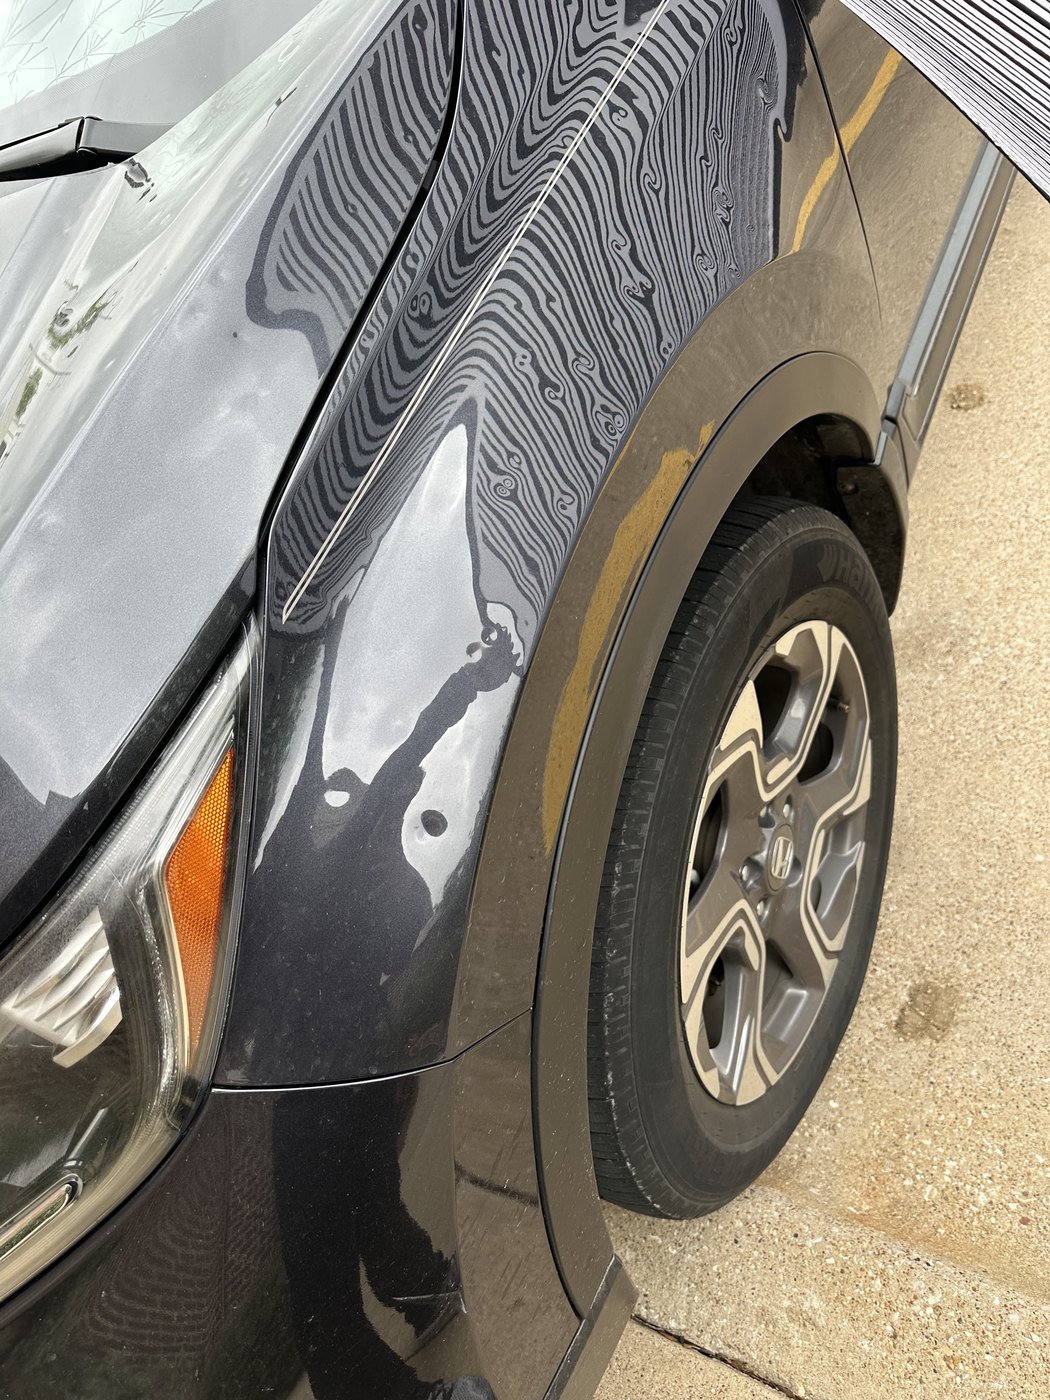
The dents you were paid for do not leave with the check. They are still on the panels the next time anybody inspects the car.
Kansas measures a car's value for total loss purposes immediately before the damage, and one of the two methods compares vehicles with regard to condition and equipment (K.S.A. 8-197(b)(7)). Old dents are part of the condition.
Before you decide, ask your carrier in writing how it would handle a second hail claim on the same panels, and how the unrepaired damage would be treated if the car were ever totaled. That answer is your carrier's to give, not ours.
Do I have to tell a buyer about unrepaired hail damage?
We cannot give you legal advice about a private sale, and this page does not. What is written down is narrower. If the car ever became a salvage vehicle, Kansas makes it unlawful to sell it without handing the buyer the salvage title (K.S.A. 8-199(a)). If you are not sure whether your claim did that, ask your insurer before you list the car.
Two more things are worth knowing before a sale. A vehicle history report is put together by companies outside the transaction, and the event that creates a record is the claim, not the repair method; only your carrier can tell you what it reports. And the department's guide says a diminished value claim, for lost resale value, is in most cases excluded under your own policy by its language.
Questions about keeping the hail check
Does the Kansas Insurance Department say I can keep the money?
Its consumer guide does not address keeping the money directly. What it does say about a repairable car is above: the check is issued in your name, and the offer has to cover the actual repair cost. If you cannot resolve a claim with your insurer, its Consumer Assistance Division takes calls at 1-800-432-2484.
Can a repair shop ask me to sign over my claim?
Read anything a shop gives you before you sign it. After storms, the department warns Kansans to be very skeptical of a contractor who pressures you to sign over your assignment of benefits, because that lets the contractor deal with the insurer without you.
If I keep the check, can I get the car repaired later?
Whether the claim can be reopened or supplemented after a cash settlement is your carrier's call, so ask before you deposit the check. The inspection is free either way.
What if the insurer says the car is a total loss instead?
Then the check is a different kind of settlement, and Kansas title rules come in. That is covered in will hail total my car in Kansas.
- Kansas Insurance Department, Auto Insurance Shopper's Guide
- K.A.R. 40-1-34, unfair claims settlement practices (Kansas Insurance Department)
- K.S.A. 40-955(g)(1), lienholder on the application
- K.S.A. 8-197, definitions (Kansas Revisor of Statutes)
- K.S.A. 8-198, salvage titles
- K.S.A. 8-199, sale of a salvage vehicle
- Kansas Insurance Department, Consumer Connection: After the storm (July 19, 2023)
Know what is on the car before you decide.
The inspection is free, takes about 30 minutes, and there is no obligation afterwards. We tell you what we find. What to do with the check is between you, your carrier and your lender.